Plan for six to twelve months of active selling once your business is officially on the market, and 12 to 36 months of preparation before that if your financials, systems, and management team need to work. The single biggest lever you control is timing your prep: start cleaning up the business well before you need to sell, and engage an M&A advisor before you talk to a single buyer.
TL;DR:
- Most sellers require 12 to 36 months of preparation for a smooth sale, including financial cleanup, SOP documentation, and management building.
- The active selling process from market launch to close typically lasts six to twelve months, with larger deals and regulatory reviews extending timelines.
- Delays often stem from unresolved quality of earnings issues, slow responses, financing bottlenecks, or regulatory hurdles that could be mitigated through early preparation.
- Engaging advisors in the proper sequence—bankers six to twelve months before marketing and legal or accounting specialists during preparation—reduces rework and shortens the timeline.
- Completing readiness work early, especially through structured programs, can significantly shorten diligence and negotiate from a position of strength.
Table of Contents
- What Does the M&A Timeline for Sellers Look Like?
- What Happens in Each Phase of Selling a Company?
- How Long Does the M&A Process Take by Deal Size?
- Why Do M&A Deals Get Delayed or Fall Apart?
- Who Should Sellers Hire, and When?
- What Should Sellers Do to Stay on Schedule?
- How AOS Shortens Prep and Diligence Time
- An Owner’s Honest Take on M&A Timing
- Compress Your Timeline Before You Go to Market
- Sources
- FAQ
What Does the M&A Timeline for Sellers Look Like?
The M&A timeline for sellers breaks into two very different clocks. The first is preparation, the quiet work of getting your business ready to withstand scrutiny. The second is the active process, which starts the day your advisor takes the company to market and ends at closing.
Most sell-side processes run six to twelve months from going to market to close, assuming the business is genuinely ready. Owners who skip preparation, or discover mid-process that their books need rework, routinely see that window stretch past a year. Preparation itself can take anywhere from a few months to three years, depending on how far the business is from being sale ready.
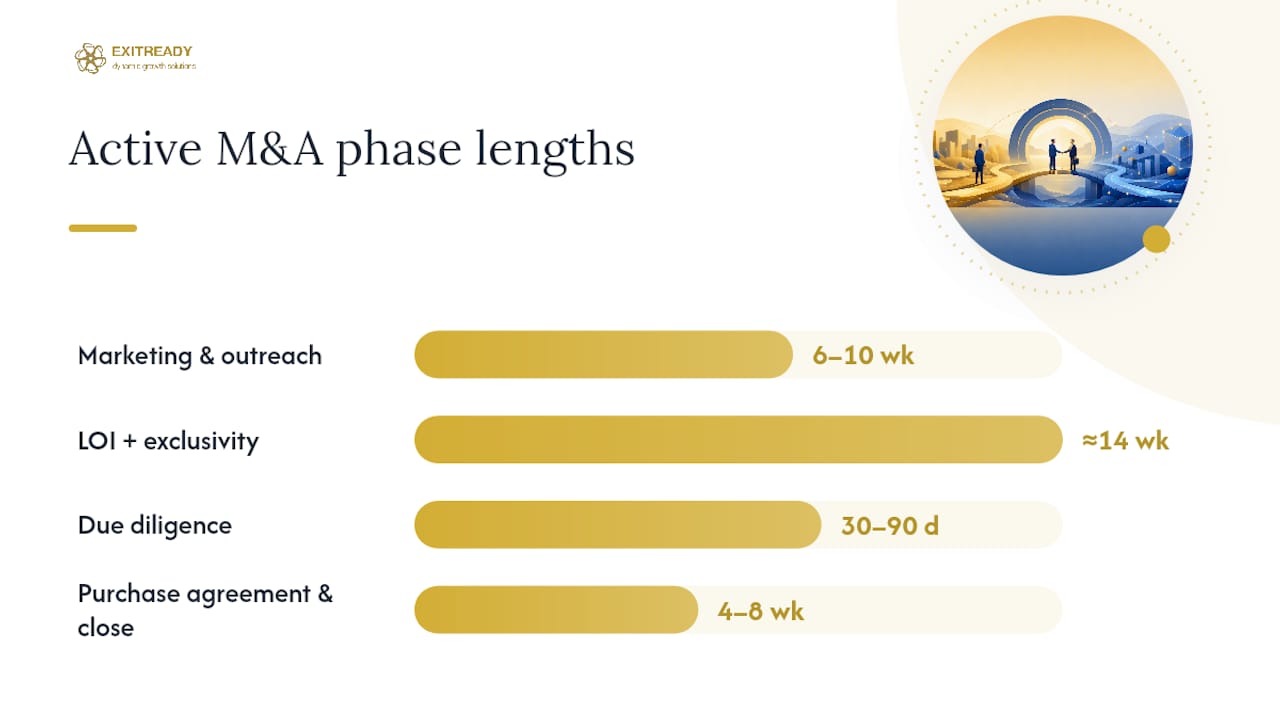
Here’s how the active phases typically break down, along with who’s driving the clock at each stage:
- Preparation (1 to 3 years, owner-led): financial cleanup, SOP documentation, reducing customer concentration, building management depth.
- Marketing and outreach (6 to 10 weeks, banker-led): CIM development, buyer list building, NDA management, initial buyer calls.
- LOI and exclusivity (2 to 4 weeks to negotiate, then 60 to 90 days of exclusivity): seller and banker negotiate terms; buyer begins deep diligence once exclusivity is granted.
- Due diligence (30 to 90 days, buyer-led): document requests, QoE review, management presentations, site visits.
- Purchase agreement and close (4 to 8 weeks, attorney-led): SPA/APA negotiation, financing finalization, closing logistics.
A market-pulse analysis of recent business sale transactions put the median time to close around 170 days, or roughly six months, though that figure moves considerably with deal size and sector. A $2 million landscaping company and a $40 million manufacturer are not playing on the same clock, even though both go through the same named phases.
What Happens in Each Phase of Selling a Company?
The phases in a merger acquisition process have consistent names across most middle-market deals, but the work inside each one is where owners either save months or lose them.
1. Preparation: fix what buyers will find anyway
This is the phase most owners underestimate. Buyers will discover a messy customer concentration problem, unrecast financials, or undocumented processes during diligence, whether you address them now or not. The only choice is whether you fix them on your timeline or theirs.
Recasting three years of financials to reflect true earning power typically takes four to eight weeks with a competent accountant. Documenting core SOPs and building a management bench deep enough that the business doesn’t collapse without the owner can take six months to two years, depending on how owner-dependent operations currently are. Advisors commonly recommend starting 24 to 36 months ahead of a target sale specifically so this work doesn’t compress the active process later. Sellers who compress preparation most effectively focus on three things: clean, normalized financials; documented systems with real management depth; and a buyer list built from qualified, not just interested, targets.
2. Marketing and outreach: the CIM does the heavy lifting
Your banker builds a teaser and a Confidential Information Memorandum (CIM), then works a curated buyer list under signed NDAs. This phase usually runs six to ten weeks. The pace depends heavily on how “sale ready” the CIM is on day one. A CIM built on stale or inconsistent numbers gets kicked back by serious buyers and adds weeks nobody planned for.
Management presentations happen toward the end of this phase, once a shortlist of interested buyers has cleared initial screening.
3. LOI and exclusivity: your leverage peaks, then drops fast
Once a buyer signs a Letter of Intent, exclusivity periods of 60 to 90 days are standard in middle-market deals. An LOI is typically non-binding on final price, but the confidentiality and exclusivity provisions bind immediately, and that matters because your negotiating leverage drops the moment you take other buyers off the table.
Pro Tip: Before granting exclusivity, get the buyer’s financing plan, key diligence contingencies, and target closing date in writing. A vague LOI gives the buyer months of free option value while you’re locked out of other conversations.
4. Due diligence: where timelines actually break
Due diligence after LOI typically runs 30 to 90 days for middle-market deals. Quality of Earnings (QoE) review, legal document requests, customer and contract review, and management interviews all happen in parallel. When the buyer needs third-party financing, lender underwriting commonly adds another 60 to 90 days on top of that, because the lender’s own timetable often becomes the real bottleneck for LOI-to-close, not the buyer’s.
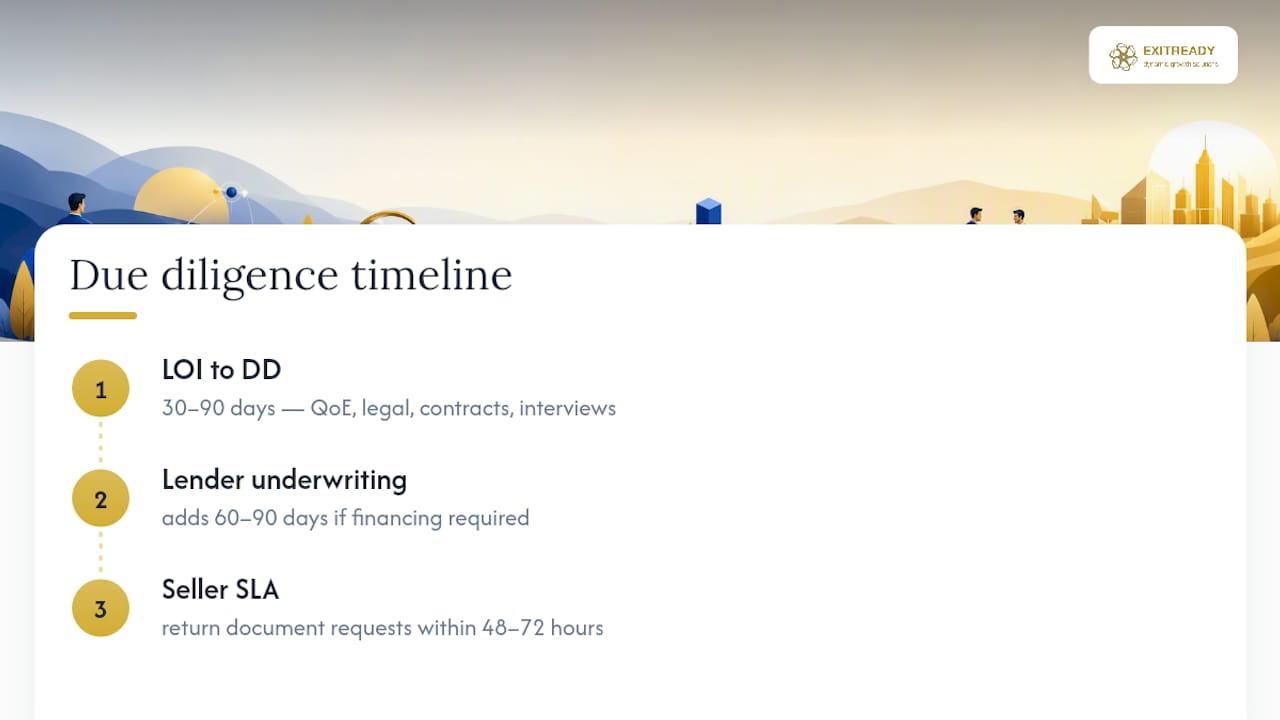
Set an internal SLA now: seller-side teams should return document requests within 48 to 72 hours. Slow responses are the single most common self-inflicted delay in this phase.
5. Purchase agreement and close: the final sprint
Negotiating and signing the definitive purchase agreement, the SPA or APA, usually happens in parallel with final diligence and takes roughly four to eight weeks. This is where price adjustments, representation survival periods, and escrow mechanics get finalized. Reps and warranties typically survive 12 to 24 months post-close, with fundamental reps often running longer. Escrow amounts, working capital pegs, and any earnout structure get locked in here.
Unresolved QoE findings or a disputed working capital calculation are the two most common reasons this phase runs long. Both are avoidable with the right prep, which is exactly why the sell-side due diligence work happens well before this stage, not during it.
How Long Does the M&A Process Take by Deal Size?
Deal size changes almost everything about pacing, from how many buyers show up to how long financing takes to clear.
| Deal Size Band | Typical Active Timeline | Key Timeline Factor |
|---|---|---|
| Main street (under $1M) | 4 to 8 months | Often cash or seller financing; fewer diligence layers |
| Lower middle market ($1M to $5M) | 6 to 10 months | SBA financing common, adding 60 to 90 days of underwriting |
| Middle market ($5M to $40M+) | 6 to 12 months | Full QoE, legal diligence, possible PE buyer processes |
| Large/regulated deals | 12 to 36 months | HSR filing review may apply |
SBA-backed buyers introduce a lender underwriting timeline that frequently governs how fast an LOI can turn into a closing, regardless of how ready the seller is. Larger deals crossing the Hart Scott Rodino Act’s minimum size-of-transaction threshold, set at $133.9 million effective February 17, 2026, face a standard 30-day federal antitrust waiting period. Most middle-market deals fall well under that threshold and never trigger a filing, but if yours is close to it, flag it with counsel early. A second request from the FTC or DOJ can extend review well past a year in the rare cases where it happens.
Why Do M&A Deals Get Delayed or Fall Apart?
Delays rarely come from one catastrophic event. They usually come from a handful of predictable friction points that compound if nobody’s watching for them.
- QoE surprises: unrecast add backs, inconsistent revenue recognition, or unclear customer contracts can add four to six weeks to diligence when discovered mid-process instead of during prep.
- Financing delays: SBA and conventional lender underwriting can add 60 to 90 days beyond the buyer’s own diligence timeline.
- Regulatory review: HSR filings are uncommon below the $133.9 million threshold, but a second request in the rare case it applies can extend the process by over a year.
- Working capital disputes: true-ups typically settle within 60 to 120 days post close, and disagreements over methodology are one of the most common post-closing conflicts.
- Slow seller response: every week a document request sits unanswered is a week added directly to the closing date.
The median time to close hovers around 170 days for a well-run process, but that number assumes reasonably prompt responses on both sides. A seller team that treats diligence requests as a low priority routinely pushes their own closing back by months, entirely by accident.
Who Should Sellers Hire, and When?
The order you bring in advisors matters almost as much as who you hire. Getting the sequence backward is one of the quieter ways owners lose months.
- Investment banker or M&A advisor: engage 6 to 12 months before you plan to go to market. They build the CIM, run the buyer process, and manage negotiating leverage throughout.
- Sell-side counsel: bring in during preparation, not after an LOI arrives. Early legal review catches contract and IP issues before a buyer’s lawyers do.
- QoE and accounting specialists: engage during preparation, ideally 6 to 12 months out, so financials are already clean when diligence starts.
- Industry, environmental, or IP specialists: bring in once you know your buyer pool; not every deal needs them, but regulated industries or asset-heavy businesses often do.
A coordinated team that has already talked to each other before a buyer shows up avoids the single biggest source of diligence rework: three advisors giving three different answers to the same buyer question. The role advisors play in exit transactions shapes far more of your timeline than most owners expect going in.
What Should Sellers Do to Stay on Schedule?
A concrete plan beats a vague sense of urgency every time. Here’s a sequence that keeps most middle-market deals on track.
- 12 to 36 months out: recast financials, document core SOPs, build management depth, address customer concentration.
- 6 to 12 months out: engage a banker, begin CIM development, address any legal or contract cleanup flagged by counsel.
- 3 months out: finalize the CIM, build the buyer list, prepare the data room structure in advance.
- Active marketing (weeks 1 to 10): respond to buyer questions within 48 hours; track NDA signings weekly.
- LOI to close: hold document response times to 48 to 72 hours; hold weekly calls with your banker and attorney to track open diligence items.
| Timeframe | Owner’s Main Job | Risk If Skipped |
|---|---|---|
| 12 to 36 months out | Clean financials, document systems | QoE surprises during diligence |
| 6 to 12 months out | Hire advisors, prep CIM | Slow start once market-ready |
| 3 months out | Build data room | Delayed buyer response times |
| Active process | Respond fast, stay coordinated | Added weeks per slow response |
A full multi-year version of this calendar, with week-by-week detail, lives in the timeline planning guide for business exits.
How AOS Shortens Prep and Diligence Time
Most of the delay in a sell-side process traces back to the same three gaps: messy financials, undocumented operations, and an owner the business can’t function without. Dynamicgrowthsolutions built its Accelerated Operating System, AOS, specifically to close those gaps before a buyer ever sees the business.
AOS replaces owner dependency with documented playbooks and delegation systems, the exact readiness work that normally eats months of the preparation window. Financial cleanup, SOP documentation, and management-depth building happen as structured deliverables rather than open-ended projects. For owners planning ahead, that groundwork pairs directly with the multi-year exit timeline and the private equity sale playbook for those targeting a PE buyer specifically.
An Owner’s Honest Take on M&A Timing
Owners who wait until they’re “ready to sell” to start preparing almost always lose leverage they didn’t know they had. Do document your systems now, even if a sale is years away. Don’t let your CIM go out before your financials are truly clean; buyers punish that instantly. Don’t grant exclusivity without getting financing contingencies in writing first.
Starting early isn’t caution. It’s the difference between negotiating from strength and negotiating from exhaustion three months into diligence.
— Andre
Compress Your Timeline Before You Go to Market
Every phase covered above gets shorter when the business is genuinely ready before a banker ever picks up the phone, and that’s the exact gap Dynamicgrowthsolutions closes. Rather than a traditional consulting retainer that bills by the hour while you wait on deliverables, the Growth Sprint, Performance Sprint, and Enterprise Sprint programs are structured, fixed-scope engagements built to fix the specific gaps that slow diligence: messy financials, undocumented SOPs, and thin management benches.
Owners who complete this readiness work ahead of going to market typically walk into buyer conversations with fewer open questions, which means fewer diligence surprises and a stronger negotiating position at LOI. If you’re not sure where your business stands today, the Growth Readiness Score Card gives you a fast, no-cost read on your biggest gaps. From there, schedule a strategy call to map out exactly which readiness work would shorten your specific timeline before you talk to a single buyer.
Sources
- Middle Market M&A timeline: what to expect | GNS Law PLLC
- Selling a Business Timeline: What to Expect · Iconic
- Buy-side mergers and acquisitions process | DealRoom
- Merger and acquisition process flow chart — Legal Clarity
FAQ
What Is the Typical Timeline for an M&A Deal?
Most middle-market M&A deals take six to twelve months from going to market to close, not counting preparation. Add preparation time, which can run 12 to 36 months depending on how ready the business’s financials and systems already are, and the full picture stretches considerably longer.
Why Do So Many M&A Deals Fail to Close?
Deals commonly fall apart or stall due to unresolved QoE findings, financing that doesn’t come through on schedule, or disputes over working capital methodology after the LOI is signed. Poor preparation is the root cause behind most of these, since a business with clean financials and documented operations gives buyers far less to object to during diligence.
What Is the Typical Timeline for a Sell-Side M&A Process?
A sell-side process typically breaks into preparation (1 to 3 years), marketing and outreach (6 to 10 weeks), LOI and exclusivity (60 to 90 days), due diligence (30 to 90 days), and purchase agreement negotiation (4 to 8 weeks). There are programs designed specifically to shorten the preparation phase by fixing financial and operational gaps before marketing begins.
How Long Does a Typical M&A Process Take Overall?
From first advisor conversation to closed deal, most well-prepared middle-market sellers complete the full process in six to twelve months of active work. Sellers who haven’t prepared their financials or systems in advance often see that stretch well past a year once diligence surfaces issues that should have been fixed earlier.